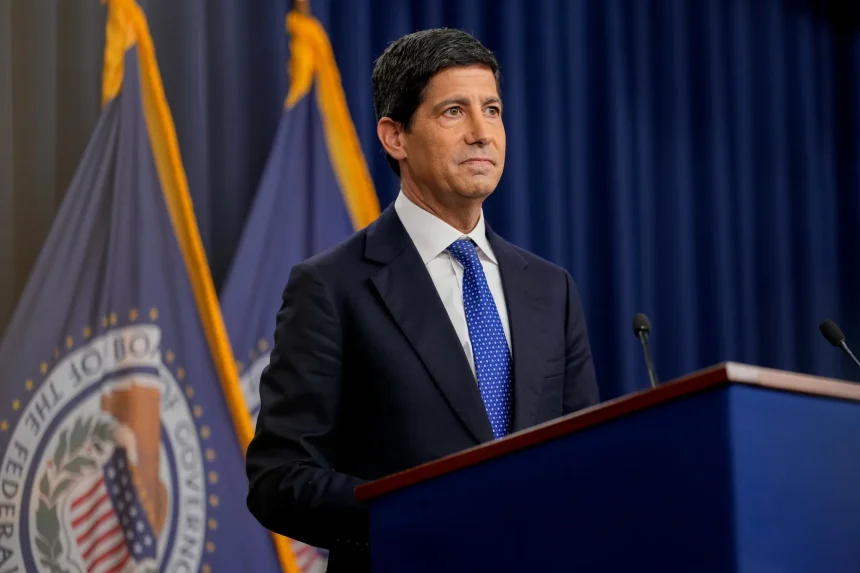
Treasury yields have spent October hovering near two-decade highs, with the 10-year note briefly topping 5.3% before easing back toward the 5% mark. Against that backdrop, a growing number of investors have been building positions that assume the next move is down, betting the Federal Reserve is closer to cutting than hiking. The problem is that the Fed itself has been sending a very different signal.
Futures markets tell the story of how quickly the mood has shifted. Traders are now pricing in a 73% chance of a December rate hike, up sharply from just 42% a month earlier. A CNBC survey around this week’s Fed meeting found 93% of respondents expecting a pause for now, but 76% still anticipating a hike in December, a combination that points to a central bank holding steady in the near term while keeping the door open to tightening further.
That hawkish lean sits awkwardly next to the positioning building up in Treasury markets. Some investors, including bets flagged by major brokerages, have leaned toward expecting a December rate cut rather than a hike, a split in outlook that leaves the bond market more exposed than usual to a sharp repricing if the Fed’s December decision lands on the hawkish side of that divide.
The stakes of getting it wrong are not small. Inflation pressures tied to surging energy prices and the continued buildout of AI infrastructure have given policymakers reasons to stay cautious about declaring victory too early, even as softer patches of economic data give bond bulls something to point to in making the case for cuts. The Fed's own messaging has tried to balance both: a measured pace, paired with a clear unwillingness to rule out further hikes.
For investors who have already built bullish Treasury positions on the assumption that yields have peaked, a hawkish December decision would force a fast unwind, the kind of reversal that tends to move yields sharply in a short window as crowded trades get closed out at once. That risk is precisely what has kept the bond market on edge even as headline yields have pulled back from their October highs.
The next major test comes with the Fed's December meeting, where the gap between what traders are pricing and what some economists still expect will likely resolve one way or the other. Until then, the bullish Treasury trade remains a bet not just on where rates are headed, but on how confidently the Fed is willing to signal it before getting there.